Refreshing! Made with the assistance of our friend, ChatGPT
Here’s some High and Low, followed by a thought on Where We Go.
Where We’ve Been.
State Programs. We’ve given you the skinny on state Auto IRA assets and account growth, above. Here are a few more 2026 milestones. We should save this for year end, but we’re not going to. We’ve got something special planned for the December edition.
New programs launched and launching: Minnesota, in January. (Brrrr) New York’s deadlines began to take effect in March, May and July. Hawaii is targeting December.
State and City legislation: Mississippi enacted an opt-in program in April—stay tuned. And PhillySaves passed locally and looks like it will be the first city-based program to launch, in 2027. Philadelphia is as big as some of our smaller states, and we think they are well poised for success.
Auto IRA assets passed the $3 billion mark this spring. We think we’re saving the $4 billion milestone for next year but WHO KNOWS.
And, in a good-guys-also-win moment, it turns out that states with Auto IRA programs experience excellent growth in private sector new plan formation. We like new plans. Also, they use auto-enroll.
Federal Action.
After some breath-held waiting, the federal Saver’s Match is squarely on plan for implementation in 2027 (the awareness, contribution, and construction year) and 2028 (the first match payout and fine-tuning year). It came with some important guidance—IRS Notice 2026-48—useful for industry and others working on this initiative. Stay tuned for regulations to follow the comment period, which closed October 5.
February’s State of the Union address brought the delightful surprise announcement of TrumpIRA.gov—coming soon to a location near you. We like the integrated Saver’s Match acceptance requirement, and the use of a lot of earned media to promote this marketplace into the corners of America where today’s DC and DB plans, auto IRA and other retirement arrangements are NOT YET REACHING.
Trump Accounts for kids, arguably, satisfy a range of policy goals. We hear all of you shouting at us right now. We’ll just say, we like the idea of getting way more American kids and families ‘on the bike’ of an early investment account. We like the idea of more kids achieving early adulthood with assets they wouldn’t otherwise have had. This is a great social experiment and we can’t wait to see how it evolves. We like the idea of the accidental/intentional, we don’t know which, Child IRA account. Cuz, #retirement.
And, we like that the conversation around a federal standard for workplace retirement savings access stays visible. Perhaps in back rooms we are refining our thoughts about what really works: one and two. This policy piece from our friends at BPC says more, and expresses their current view. BPC also talk about Auto IRAs and new plan formation, which we like.
Industry Innovation (and adoption).
It is hard to make new stuff in the private sector! Partly because adoption takes forever and product profitability timelines can run out before a good idea gets traction. We have some wins though.
Emergency savings – Workplace. Access. Is. Slowly. Growing. BlackRock’s ESI report for 2026 reflects that their initiatives have achieved $7.9 billion saved across a reach of 22 million workers. See page 5 for more detail. And yes, this was a higher set of figures than we were expecting to see.
Automatic enrollment – use, impact and analysis continues. This year, Vanguard reports a shift in the use of auto-enroll from 10% of their plans in 2006, to 61% of plans in 2025. The use of all three automatic levers has increased (enrollment, escalation, investment choice). And initial contribution rates are up—62% of plans studied now use a rate of 4% or more.
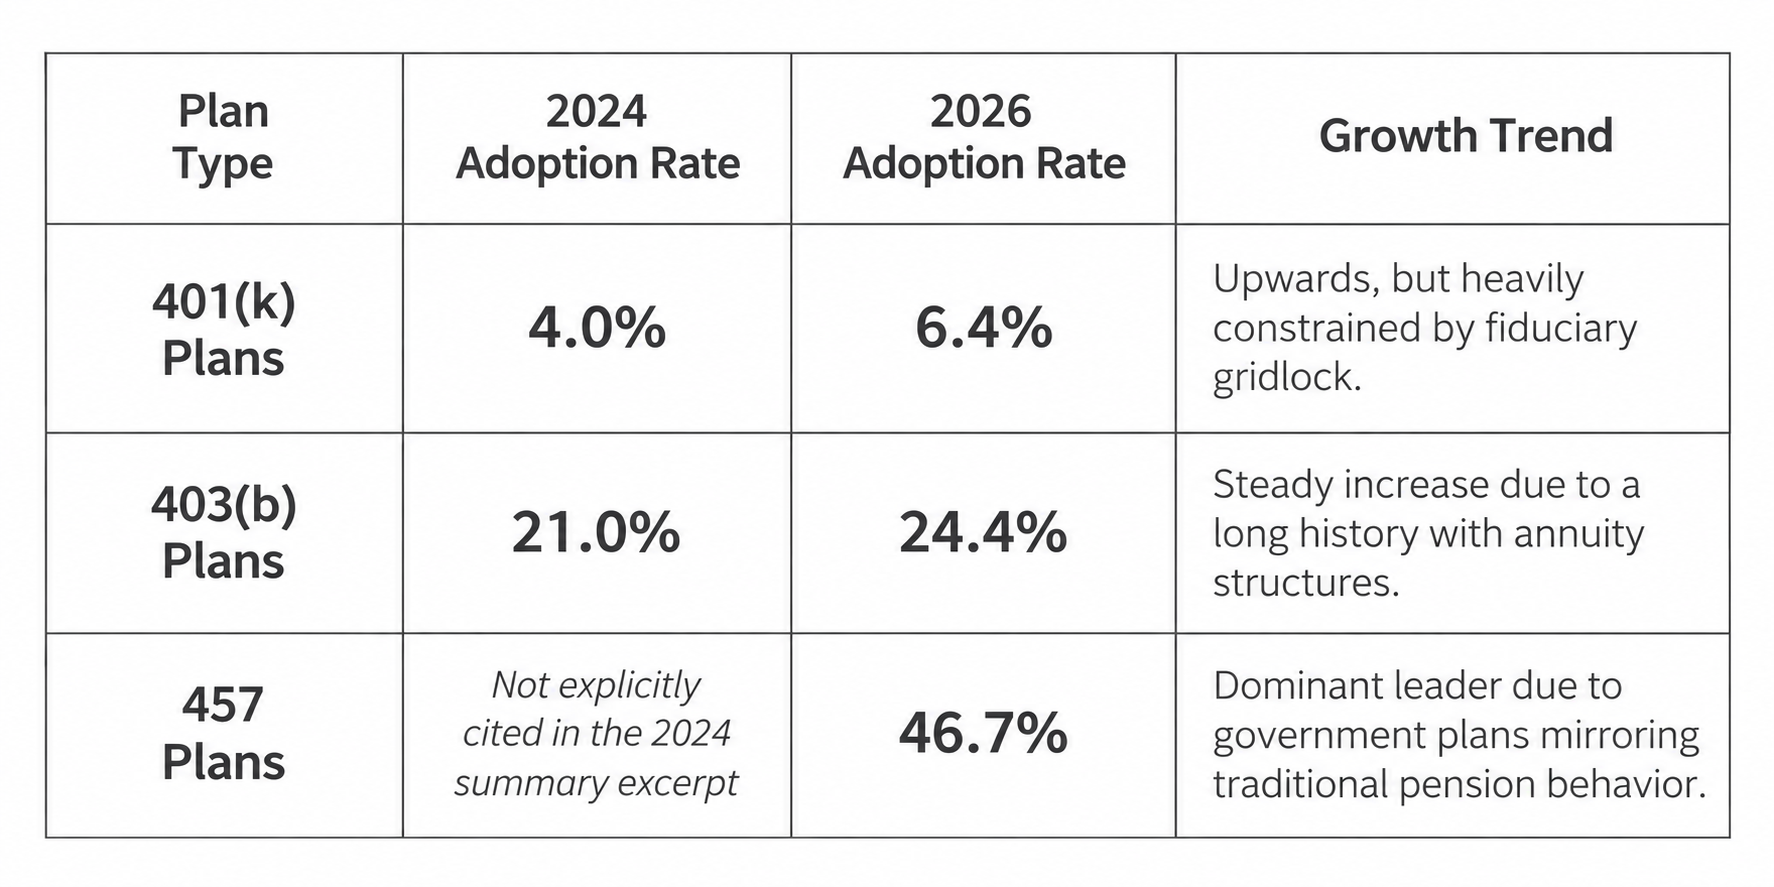
Lifetime income - these were forecasts: one and two. This is reality: 44% of recordkeepers said they do not support recordkeeping for available in-plan retirement income products. This will slow 401(k) plan adoption. Good news: PlanSponsor surveys—we find just two—show that adoption has risen over the last several years. Here’s a little chart for you:
Comparing the 2024 PLANSPONSOR Survey to the 2026 PLANSPONSOR Survey highlights how adoption rates have evolved -- see their chart here:
Where We’re Going.
OK, hear us out. Predictions for the 2027-2028 season. No particular order. Come back next year and see how we did.
1 – federal legislation passes establishing a workplace retirement savings access standard, and allowing current Auto IRA programs to serve employers across state lines. New plan formation leaps; the coverage tide (see what we did there) continues to come in.
2 – the Saver’s Match rolls out. LMI taxpayers, many many of whom have saved in matchable ways, have to use Form 8880-A to claim their refundable credits. It’s a pain in the neck but with a lot of environmental support, more than half of them are successful. Small balances leap upward. The program receives formal and information evaluation and analysis and everyone involved in the matching process tunes up their processes ahead of the 2028 tax season (in 2029).
3 – TrumpIRA.gov launches to some fanfare and with the challenges facing any new voluntary, marketplace solution. It achieves adoption in corners of the USA where the workplace retirement account has not reached. It too receives evaluation and continues to evolve and improve.
4 – adoption rates rise meaningfully for the slow-but-important retirement-supporting tools of workplace Emergency Savings and in-plan (plan-linked?) retirement income. “Meaningfully” means, a growth rate of at least 25%, year over year. We know the base is low, but that’s a good number, yes?
5 – and, while we are waiting for #1 to happen and in the interest of excellence for their populations, five more states and large cities adopt and launch Auto IRA programs.
THAT’S ALL WE ASK.
6 – ok, one more. AI becomes a useful tool for curated, personalized, point-in-time retirement security engagement and guidance.